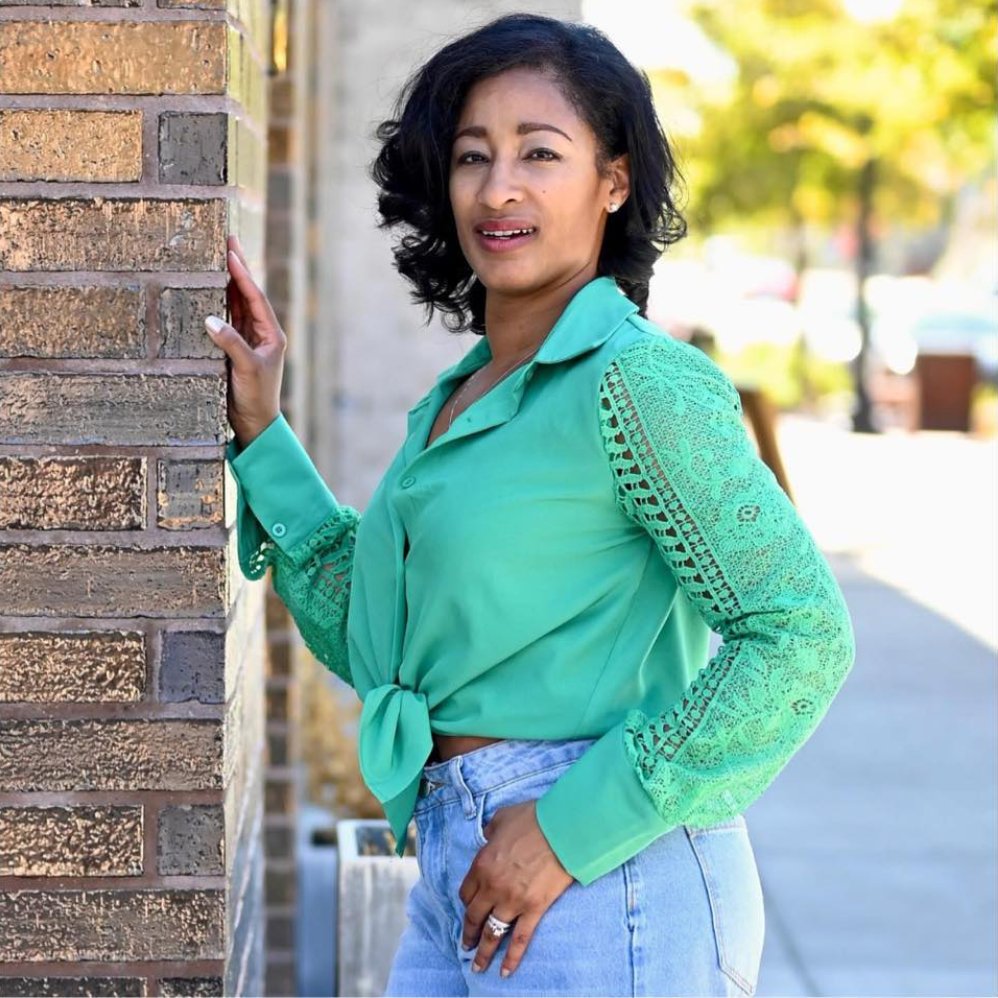
Tolechia Lane Realtor License ID: 0678848
Tolechia Lane
I’m not here to convince you to make a move. I’m here to help you figure out whether the move makes sense.
With 10 years in real estate, I help buyers and sellers navigate the decisions behind the transaction—not just the transaction itself.
Whether you’re buying your first home, moving into something that fits your life better, selling, or looking for more space and land, my approach is simple:
Understand the goal. Explore the options. Make the move that makes sense for you.
FIRST HOME
Ready to Become a Homeowner?
Start with a strategy that helps you understand your options, prepare for the process, and buy with confidence.
EXPLORE FIRST HOME
MOVE-UP HOMES
Ready for What's Next?
Your next home should fit the life you're living now—not just give you more square footage.
EXPLORE MOVE-UP HOMES
COUNTRY LIVING
Looking for More Space?
Discover acreage, privacy, and a different pace of life in the communities surrounding Fort Worth.
EXPLORE COUNTRY LIVING
How I Help
Real estate is a big decision. I’m here to help you understand your options, make informed decisions, and move forward with confidence—without the pressure.




Life, Homes & Real Talk


If you’ve been looking for a home in Crowley, come take a look at this one Sunday. 🏡
I’ll be hosting an Open House at 4332 Sweet Clover Lane from 1–3 PM.
3 bedrooms + office
Open living spaces
Split primary suite
Covered back patio
Conveniently located near I-35, I-20 & Chisholm Trail
$309,900
Come walk through it, see the space for yourself and see if it feels like home.
📍 Sunday | 1–3 PM
4332 Sweet Clover Lane, Crowley, TX
Hope to see you there!
https://www.fortworthliving.net/d8r5t9sj
#FortWorthRealEstate #FortWorthHomes #OpenHouse #TexasHomes

🏡 What if your current home could help pay for your next one? 👀
Most people think about selling when they’re ready to move. But depending on the numbers, keeping your home as a rental could be another option!
Let’s look at two examples. 👇🏽
🏡 Scenario 1: You’re ready for more space.
You bought your first home a few years ago, and now your family needs room to grow.
Let’s say your home rents for $2,200/month, and your monthly mortgage, taxes, insurance, and other regular ownership costs total $1,900.
That leaves a potential $300/month surplus before any additional expenses not already included.
🏡 Scenario 2: You’ve owned your home for years.
Maybe you’ve been in your home for 8, 10, or even 15 years. Your mortgage balance may be lower, and you’re ready for a new chapter.
Let’s say your home rents for $2,400/month, and your monthly ownership costs total $1,700.
That leaves a potential $700/month surplus before any additional expenses not already included.
Depending on your situation, that income could help offset some of the cost of your next home’s mortgage while you continue building equity in both properties.
Of course, these are hypothetical examples, not guaranteed profits. Vacancies, repairs, maintenance, property management, and other costs can affect your actual cash flow. You also need a plan for your next down payment and closing costs and to qualify for the new mortgage.
The point? You may have more options than you think! Your next move doesn’t always have to mean letting go of your current home.
👇🏽 Let’s talk! If you could make the numbers work, would you keep your current home as a rental or sell it and use the equity toward your next home?
#LetsTalkWithTolechia #FortWorthAndBeyond #DFWRealEstate #RealEstateStrategy #BuildingWealth

A little behind the scenes… 💻🏡
I’ve been putting some time into my website lately, making a few updates to better reflect how I work and the different real estate goals I help people navigate.
Whether you’re buying your first home, looking for more space, or dreaming about country living, I want you to have a place to start exploring your options.
Because real estate isn’t one-size-fits-all, and neither is the way I help my clients.
If you haven’t visited in a while, take a look around. I’d love for you to see what I’ve been working on! ❤️
🌐 www.fortworthliving.net
#TolechiaLane #FortWorthRealtor #DFWRealEstate #FortWorthLiving #HomeAndLifestyle
View More